
Carbon Black Daily: Cost Support Weakens, Rally Pauses
Carbon Black Daily: Cost Support Weakens, Rally Pauses
Market Review
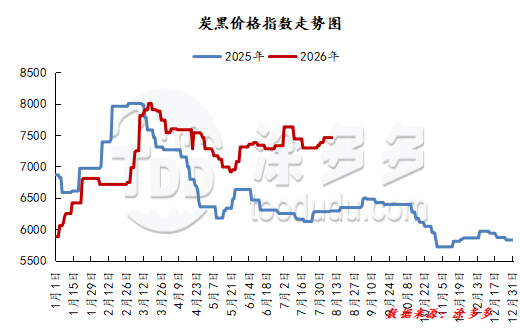
As of today, domestic carbon black prices have remained broadly stable: Shandong at CNY 7,500/tonne, Shanxi at CNY 7,300/tonne, Hebei at CNY 7,500/tonne, Guangzhou at CNY 7,600/tonne, and Zhejiang at CNY 7,500/tonne.
Raw Materials: Coal Tar Prices Begin to Retreat
Last week, with the third round of coke price cuts taking effect, coke producers fell into across-the-board losses, and the scope and intensity of production curbs are set to expand further, forcing supply to shrink passively. Coal tar prices continued to rise, but as they climbed to high levels amid sluggish sales of downstream products, overall downstream buying sentiment fell notably and resistance emerged at high prices. Adding to this, transaction prices in the Tangshan area published by Sunday showed a slight retreat, increasing the bearish signals in the market and putting pressure on prices ahead. Therefore, the likelihood of declines this week has increased.
Domestic anthracene oil prices remained relatively firm. Last week, high-temperature coal tar showed a strong trend, providing solid cost support to the anthracene oil market. Operating rates at coal tar deep-processing plants rose, increasing anthracene oil supply, and producers mostly pushed offers higher. However, as coal tar prices in some regions weakened late last week, dampening anthracene oil selling sentiment, producers kept firm offers with an upward bias. Downstream players showed notable resistance to higher-priced anthracene oil: carbon black producers continued to wait for lower prices, and demand from anthracene oil hydrogenation units for high-priced anthracene oil was sporadic. This demand-side resistance capped the upside for anthracene oil overall.
Demand: Limited Change in Plant Operating Rates; Shipments Miss Expectations
China’s semi-steel radial (passenger car) tire operating rate stood at 65%, and the full-steel radial (truck/bus) tire operating rate at 64%. Tire makers’ operating rates diverged: some semi-steel tire plants that had been under maintenance resumed operations one after another, supporting a recovery in operating rates, while a few full-steel tire plants still had output curbs or maintenance schedules, keeping overall rates weak. In terms of the market, after restocking in the second half of last month, semi-steel tire distributors focused on digesting existing inventories in early August. Persistent hot weather in many regions improved business at some end-user stores, with replacement tire volumes up month on month, but no large-scale restocking followed. For full-steel tires, market shipments slowed in early August and channel inventories were relatively ample; to boost sales, some distributors may still offer promotions on their own. Even where selective price concessions emerged, their boost to overall transaction volumes was limited.
Overall: Weakness Across the Chain Points to Softening Carbon Black
On the cost side, after high-temperature coal tar climbed to elevated levels, downstream buying sentiment fell notably and resistance emerged at high prices. Combined with declining transaction prices in some regions, bearish signals increased, and cost support is expected to retreat. Downstream inquiries are mostly at low levels, and having signed low-priced orders earlier, buyers have reduced purchasing volumes recently. Actual deal negotiations face pressure as the market adopts a wait-and-see stance. With high costs proving difficult to digest, carbon black prices are expected to soften.









