
Carbon Black: Prices Gone Crazy(Sep 11)
Carbon Black: Prices Gone Crazy
Market Review
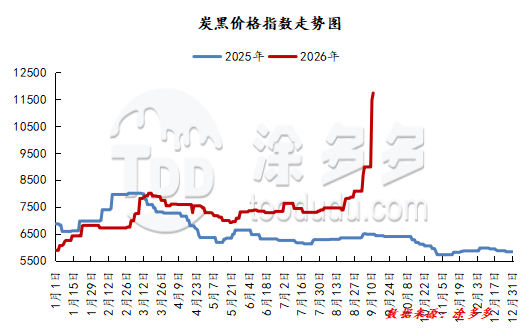
This week, carbon black prices showed a vertical surge. In just two days, the carbon black price index rapidly climbed 2,746.75 points, representing an overall increase of 30.58%. As of the end of the week, N330 quotes across regions were: Shandong region at 11,800 yuan/ton; Shanxi region at 11,600 yuan/ton; Hebei region at 11,800 yuan/ton; Guangzhou region at 12,000 yuan/ton; Zhejiang region at 11,800 yuan/ton.
Raw Materials: Coal Tar Breaks Free from Years of Suppression
Since the beginning of the month, transactions in the domestic coal tar market have increasingly reached the "5,000" level, with market bullish sentiment remaining strong. Against the backdrop of tight overall supply-demand dynamics, this round of increases does not appear to have fully reached its end. Examining the specific supply-demand dynamics driving this rally:
On the supply side, earlier sharp reductions in coking plant operating rates led to decreased coal tar output, further tightening an already supply-constrained market. Recently, shortages have become increasingly apparent. On the demand side, the market previously held certain correction expectations, with downstream plants generally keeping raw material inventories low. Current restocking demand has been concentratedly released, and the tight supply situation continues to intensify. Additionally, coal tar pitch prices have been following the uptrend smoothly, deep processing enterprises are generally operating well, and demand for coal tar remains stable.
This week, the anthracene oil market saw quotes surge significantly driven by the sharp rally on the cost side, but actual transactions have not followed through, and the market has fallen into a stalemate. The cost side was the dominant force this week. Raw material high-temperature coal tar bidding across regions was pushed up substantially, recording the largest weekly increase of the year, sharply increasing cost pressure on deep processing enterprises. On the supply side, coal tar deep processing operating rates declined during the period, with anthracene oil supply seeing a narrow reduction, but the impact of supply contraction was clearly smaller than the impact of cost-driven increases.
Against the backdrop of sharp cost increases, anthracene oil producers mostly raised quotes in tandem with coal tar increases to alleviate their own profit pressure. However, downstream absorption capacity is limited: although carbon black industry new orders were also sharply raised, the actual implementation of high prices has been poor, suppressing carbon black producers' willingness to accept high-priced anthracene oil. The other major downstream...
Demand Side: Semi-Steel Resuming, All-Steel "Lying Flat"
During the period, the tire industry operating rate showed structural divergence, with semi-steel and all-steel tires performing differently. On the semi-steel side, previously maintenance-suspended plants gradually resumed production, driving a recovery in operating rates. However, most enterprises still maintained production control measures, limiting the magnitude of operating rate recovery, resulting in limited overall recovery. On the all-steel side, although a few maintenance-suspended plants resumed operations, recent continuous rises in raw material prices pushed some规格 products into losses, intensifying enterprises' willingness to control production, dragging overall operating rates lower rather than higher.
Overall, cost pressure and production control mentality jointly dominate the current tire production rhythm. The industry's overall operating rate remains sluggish, and procurement demand for upstream raw materials is unlikely to see significant volume increases.
Comprehensive Outlook: Firm Costs, Continuing to Follow the Rally
Pre-holiday stockpiling demand continues to be released, providing phased support to the coal tar market. Short-term prices may maintain high levels, and cost-side support remains relatively solid. In this context, cost pressure on the carbon black market is difficult to alleviate, and there is no clear downward trend in prices in the short term. Considering that the raw material uptrend has not yet ceased, carbon black market quotes are expected to continue following raw material increases upward next week, and the high-level pattern is likely to persist.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.









