Carbon Black Weekly: Calm on the Surface, Competition Beneath(Nov 5)
Carbon Black Weekly: Calm on the Surface, Competition Beneath
1.1 Carbon Black Market Price Analysis
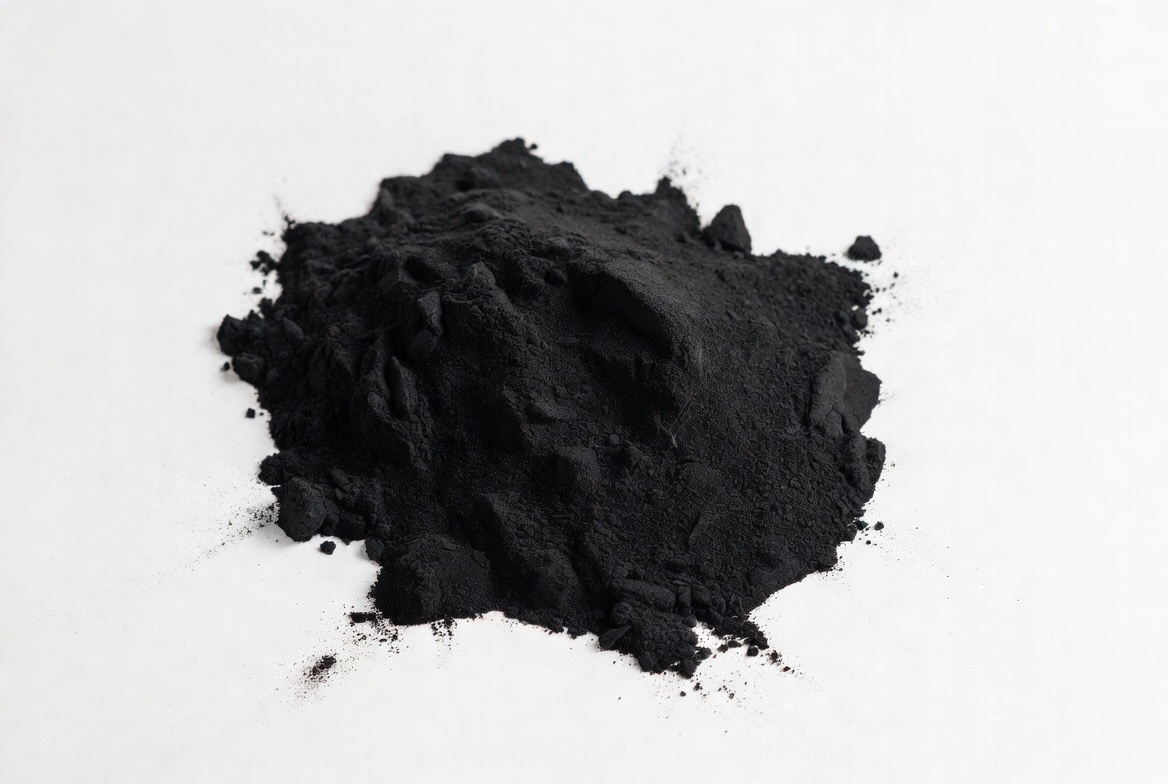
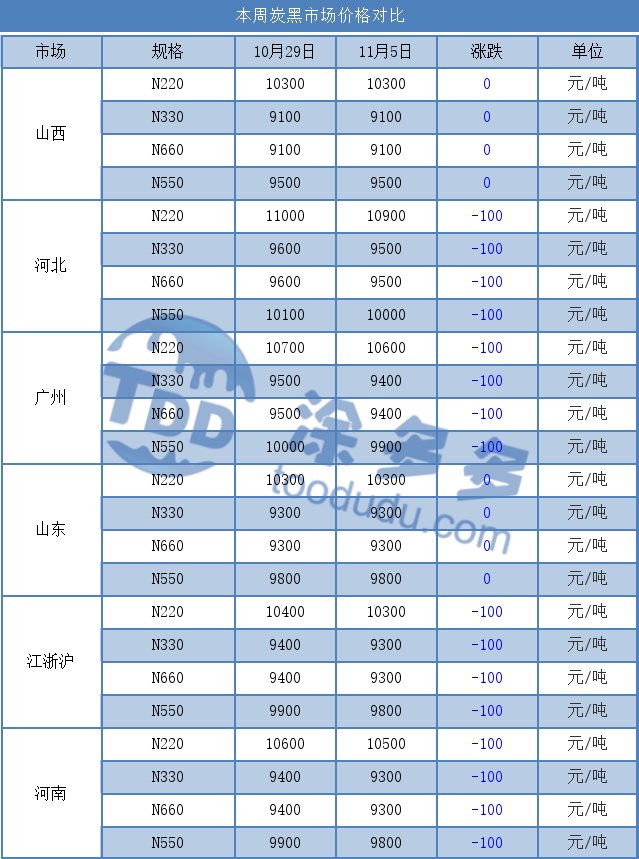
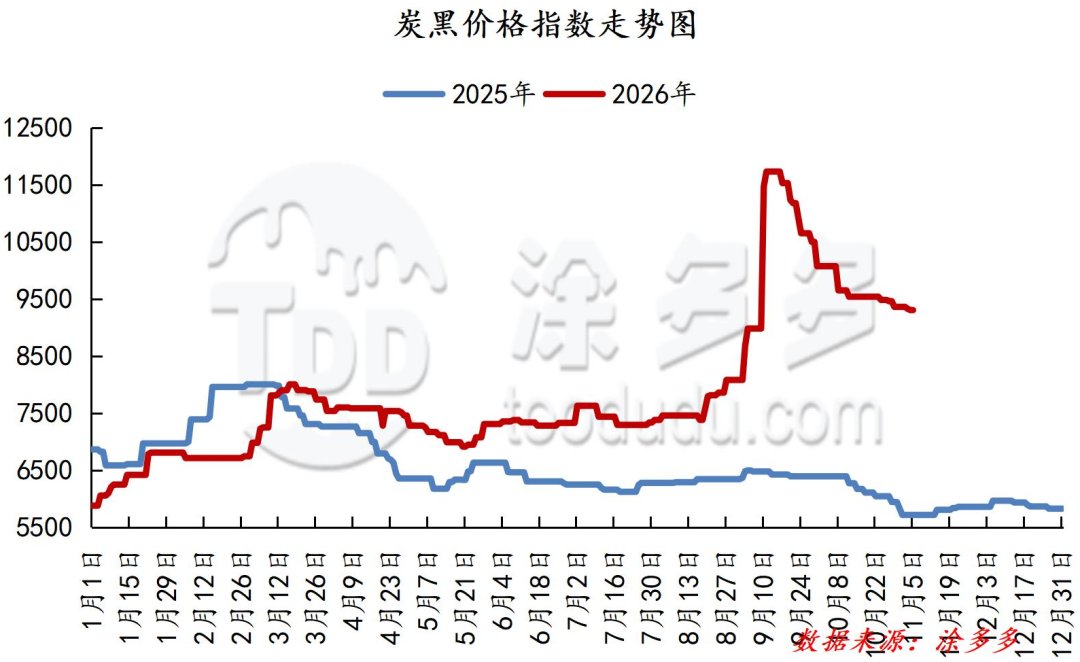
This week, domestic carbon black prices showed a slight downward trend. As of Thursday this week: Shandong region 9,300 yuan/ton; Shanxi region 9,100 yuan/ton; Hebei region 9,500 yuan/ton; Guangzhou region 9,400 yuan/ton; Zhejiang region 9,300 yuan/ton. This week, domestic carbon black market new order negotiations remained basically stable, with overall trading atmosphere flat and both buyers and sellers operating cautiously. Raw material coal tar market new orders maintained stable consolidation, with market wait-and-see sentiment gradually stabilizing, prices maintaining stable negotiations, and limited cost-side guidance. Downstream maintained essential replenishment rhythm, with procurement primarily on-demand. Transaction prices concentrated in the low range, with intensified negotiation games within the market and difficulty in achieving high-level transactions. Overall, new order fluctuations are limited in the short term, with stable shipments as the main pattern.
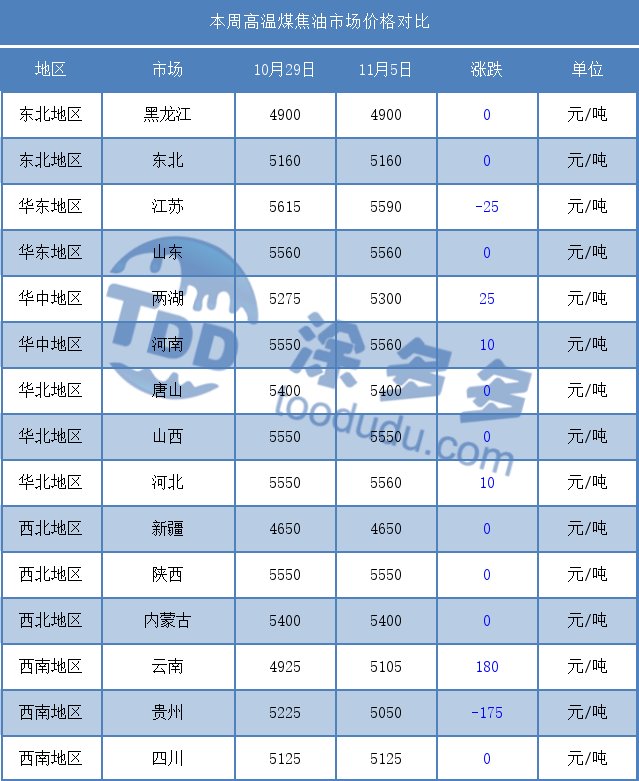
This week, domestic high-temperature coal tar market new order prices were successively released, with the overall trend still mainly maintaining stability and limited price center fluctuations. From the downstream products perspective, new order transaction prices this week were predominantly declining, with deep processing enterprises profit margins narrowing and their capacity to absorb high-priced raw materials declining. However, downstream operating rates remain at high levels at present, and high-temperature coal tar demand remains relatively strong. With essential demand support, the market bottom is relatively solid.
Additionally, deep processing factories maintain strong price-supporting sentiment with limited willingness to offer concessions, and the market continues to transition smoothly under supply-demand competition. Overall, with costs and demand constraining each other, the high-temperature coal tar market maintains stable operation.
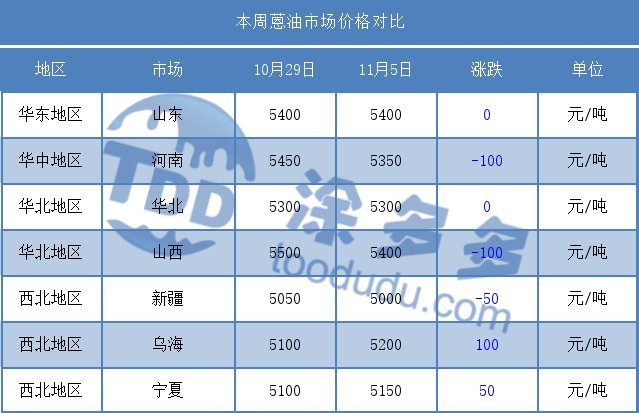
This week, the domestic anthracene oil market new orders showed a continued wait-and-see trend, with trading atmosphere within the market being subdued and both buyers and sellers operating cautiously. On the raw material side, high-temperature coal tar market new order prices were gradually released, showing a stable to slightly upward trend, with cost-side support somewhat strengthening. However, anthracene oil manufacturers maintain cautious shipping offer sentiment, with insufficient proactive offering operations, mostly waiting for raw material prices to clear before making adjustments, resulting in limited new order guidance. On the downstream carbon black side, affected by its own profit pressure and weak demand, a low-price procurement strategy is likely to persist, with limited acceptance of high anthracene oil prices and continued price-suppression sentiment, creating significant drag from the demand side on the market.
Overall, with cost-driven increases and demand-driven price suppression constraining each other, anthracene oil manufacturers face shipping pressure. The anthracene oil market is expected to operate weakly in the short term, with significant resistance to upward price movement.
Looking ahead to the next cycle, raw material coal tar market new orders are basically stable, with significant cost-side pressure supporting carbon black market new order offers. Downstream procurement continues to maintain essential demand levels, with significant price-supporting pressure for new orders in the market. In the short term, stable consolidation is expected to continue.
4. Carbon Black Industry N330 Profit Analysis
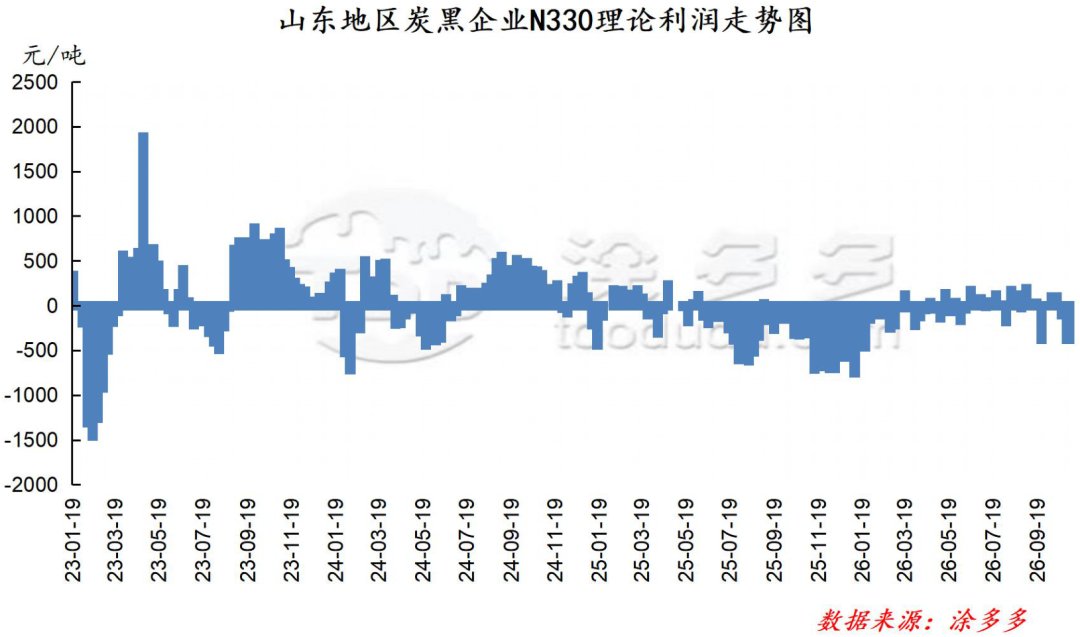
Taking the Shandong region as an example, raw material coal tar market new order tender prices are stable, and carbon black market new orders maintain price-supporting shipments. Currently, new orders have not been adjusted, and the market continues to operate at a loss. As of now, the theoretical weekly profit of the carbon black industry is -373 yuan/ton, stable compared to the previous cycle.
5. This Week Market Operating Rate Statistics
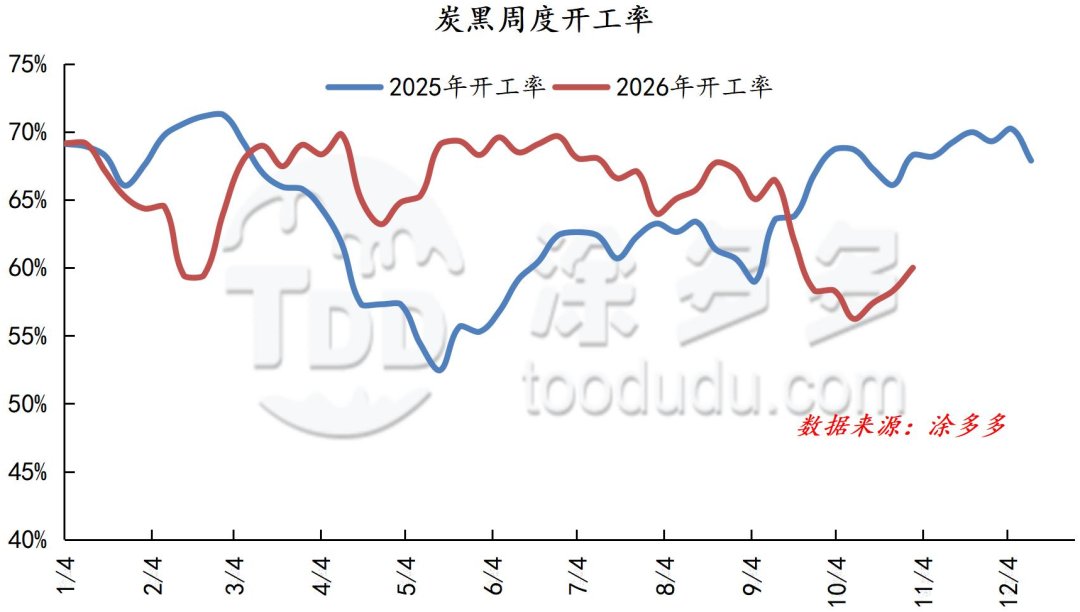
The operating rate of domestic carbon black market sample enterprises is 60%. The operating rate of domestic carbon black market sample enterprises moved up within a narrow range, with some enterprises showing both increases and decreases. However, with the heating season approaching, some enterprises have supply assurance plans, and later-stage market operating rates are expected to remain stable. Therefore, the subsequent pattern will show large factories maintaining stable operations while small factories run at low loads. Overall, carbon black market operating rate fluctuations are limited, with narrow adjustments as the main pattern.
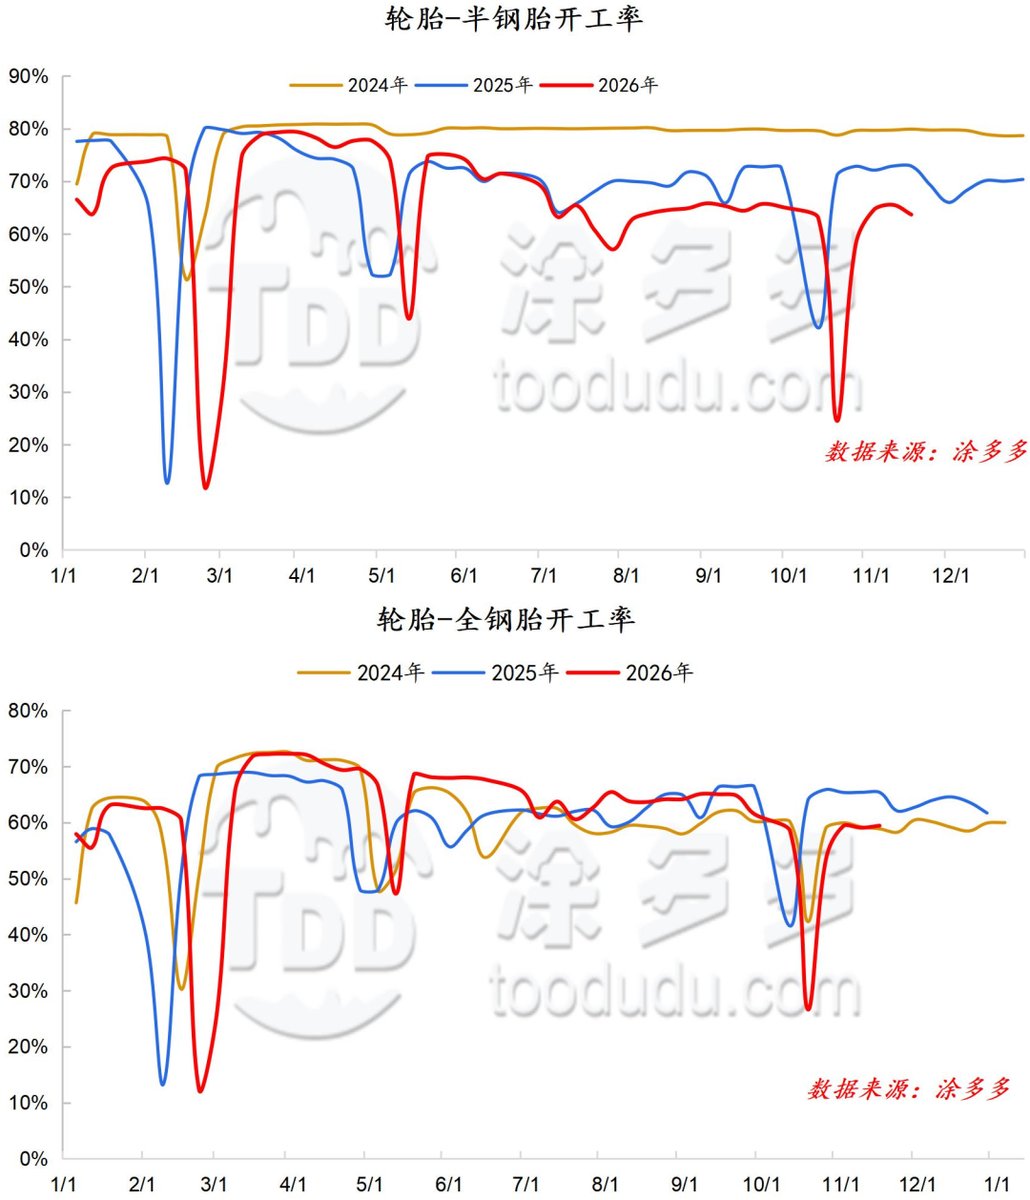
The operating rate of Chinese semi-steel tires is 64%. The operating rate of Chinese all-steel tires is 59%.
During this cycle, affected by routine maintenance at some semi-steel tire enterprises and high raw material costs, production scheduling slightly decreased month-over-month. All-steel tire enterprises remain in a flexible production scheduling state, with operating rates fluctuating within a narrow range.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.
-
Titanium Product Market Quotation(Nov 5)5451
-
Carbon Black Weekly: Calm on the Surface, Competition Beneath(Nov 5)7074
-
Natural Rubber Weekly: Rubber Prices Oscillate, Who Wins Between Bulls and Bears?(Nov 5)9606
-
Titanium Product Market Quotation(Nov 4)8053
-
Carbon Black Daily: Weak and Stable, Awaiting Direction(Nov 4)9261