
Carbon Black Weekly Report: "Surging Sharply"(Sep 10)
Carbon Black Weekly Report: "Surging Sharply"
1. Carbon Black Market Analysis
1.1 Carbon Black Market Price Analysis
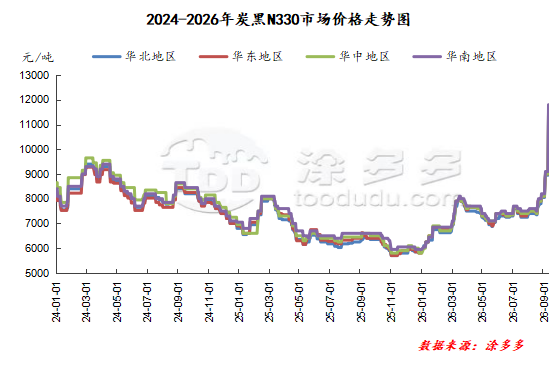
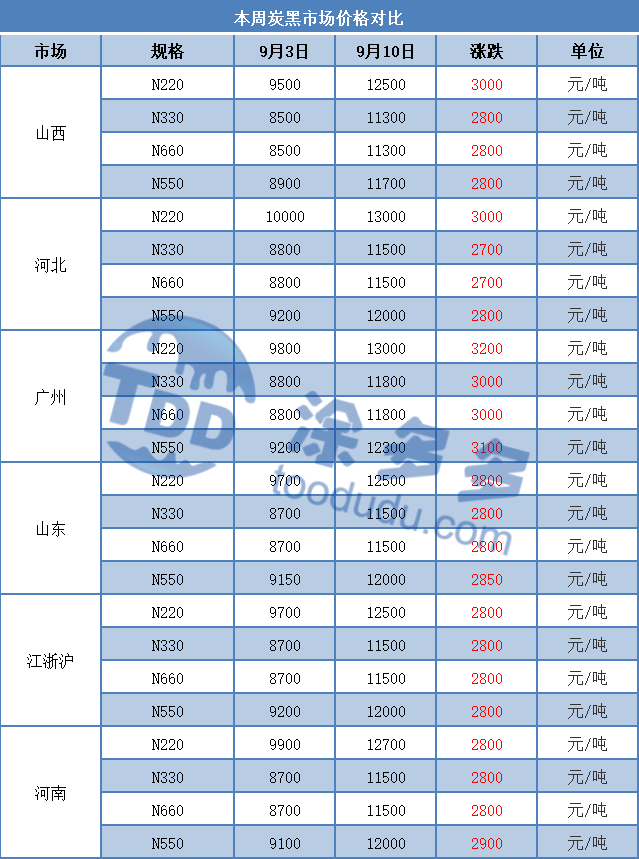
This week, domestic carbon black prices showed a pattern of initial stability followed by an uptrend, with a significant overall increase. As of Thursday this week: Shandong region at 11,500 yuan/ton; Shanxi region at 11,300 yuan/ton; Hebei region at 11,500 yuan/ton; Guangzhou region at 11,800 yuan/ton; Zhejiang region at 11,500 yuan/ton. The carbon black market exhibited a "stable first, rising later" trajectory this week. Currently, driven by strong cost-side momentum, new order quotations have risen substantially. After raw material prices underwent a round of broad increases, cost pressure has continued to transmit downstream, significantly increasing operating pressure on carbon black enterprises, and actual order quotation prices have been adjusted upward substantially. However, after the rapid price surge, downstream acceptance has become a key constraint. Terminal enterprises' resistance to high-priced supplies is intensifying, procurement is becoming more cautious, purchasing pace has noticeably slowed, and the market as a whole has entered a wait-and-see state, with a significant divergence between high prices and actual transactions. In the short term, cost logic continues to dominate the market.
1.2 Carbon Black Market Index Analysis
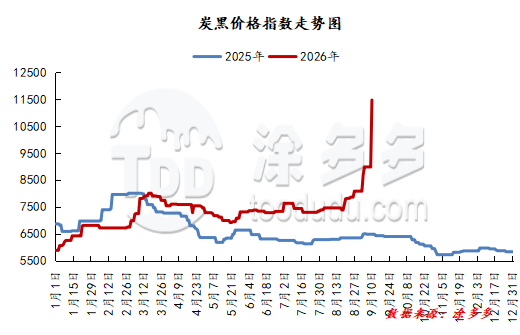
According to TuDuoduo data calculations, as of September 10, the carbon black price index stood at 11,467, an increase of 2,485.5 from the previous period.
2. Raw Material Market Analysis
2.1 Coal Tar Weekly Average Price Analysis
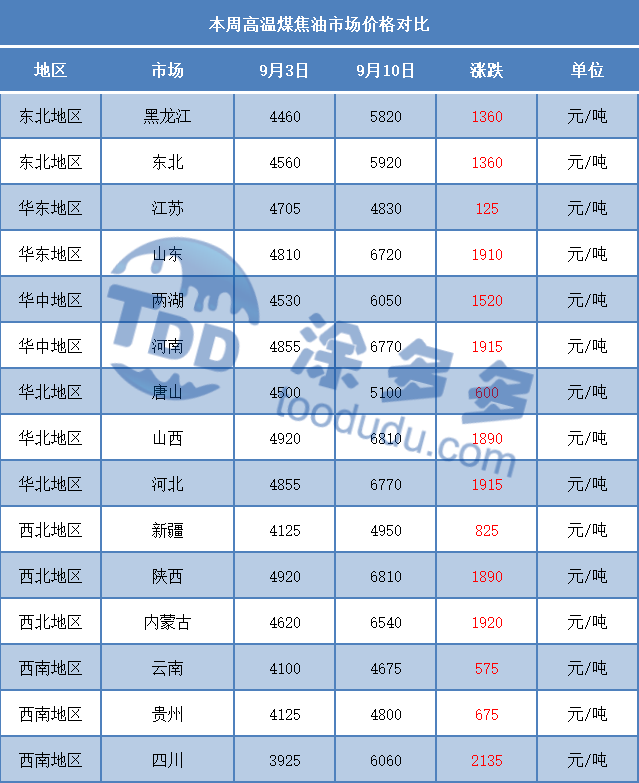
This week, the high-temperature coal tar market continued its upward surge, with the domestic high-temperature coal tar market experiencing another escalation in momentum. New order prices maintained a rapid upward trend. Auction transaction prices in the Shanxi region once again reached "sky-high" levels, refreshing historical highs. The speed of this round of increases has exceeded general market expectations, drawing widespread attention. Looking at the driving factors, on the supply side, coking enterprises are cutting output due to losses, coal tar production continues to tighten, and combined with stable operating rates at downstream deep-processing and carbon black facilities with strong rigid-demand procurement support, the supply-demand tightness has intensified, driving prices upward rapidly. However, the magnitude and speed of this increase have also raised concerns about the sustainability of high prices.
2.2 Anthracene Oil Weekly Average Price Analysis
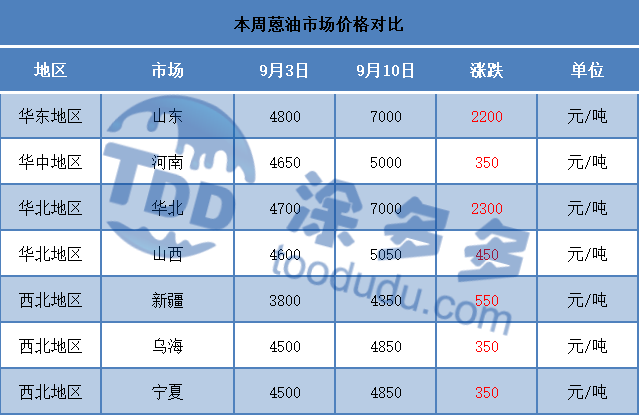
Currently, the upward momentum in the anthracene oil market continues to intensify. On the cost side, new order prices for the raw material high-temperature coal tar have been successively announced and continue to break new highs, providing strong cost support for anthracene oil upward movement. Producers' willingness to push prices higher has noticeably strengthened. However, as coal tar prices in the Shandong region have not yet been auctioned, the raw material market has not fully settled, and the cost anchor point still carries uncertainty. In the short term, the upward trend in the anthracene oil market is relatively clear, but the specific magnitude of increase will depend on the final settlement level of coal tar prices.
3. Carbon Black Market Outlook
Looking ahead to next week, domestic carbon black market new order quotations will rise substantially. After raw material market prices have broadly increased, carbon black market operating pressure is significant under cost-driven dynamics, and actual order quotation prices have risen broadly. Downstream procurement remains cautious, and after price increases, terminals find it difficult to accept the higher levels. The market is predominantly in a wait-and-see mode. The upward trend in new order prices is expected to remain unchanged, but the actual magnitude of price increases will be difficult to fully realize in transactions.
4. Carbon Black Industry N330 Profit Analysis
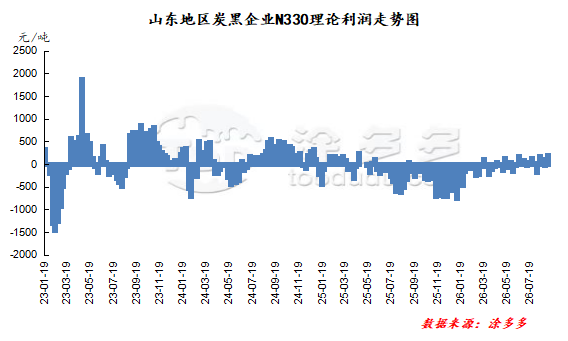
Taking the Shandong region as an example, raw material coal tar market new order prices have risen substantially, creating significant cost-side pressure. Carbon black new order prices have followed the upward trend, with the magnitude of new order increases continuing to expand during the week, but not matching the raw material market increase. Therefore, based on theoretical calculations, carbon black market profitability has declined, though it remains in a profitable state. As of now, the theoretical weekly profit for the carbon black industry is 29 yuan/ton, compared with -160.5 yuan/ton in the previous period.
5. Operating Rate Statistics This Week
5.1 Carbon Black Market Operating Rate Analysis
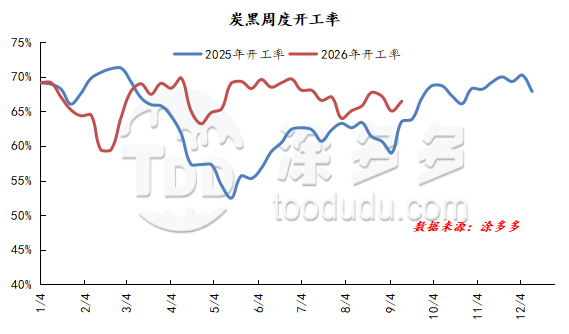
The operating rate of sampled enterprises in the domestic carbon black market was 66%. The operating rate of sampled domestic carbon black enterprises showed a narrow increase. A major manufacturer in the Shandong region completed maintenance and resumed operations, driving a regional operating rate increase. However, after the recent broad surge in raw material coal tar prices, new carbon black order shipments face difficulties, with most execution focused on previous low-price orders. Carbon black market operating pressure is excessive, and carbon black enterprises have plans to reduce loads. Some major manufacturers have cut production lines. Overall, the increase in carbon black market operating rate is limited.
5.2 Downstream Market Operating Rate Analysis
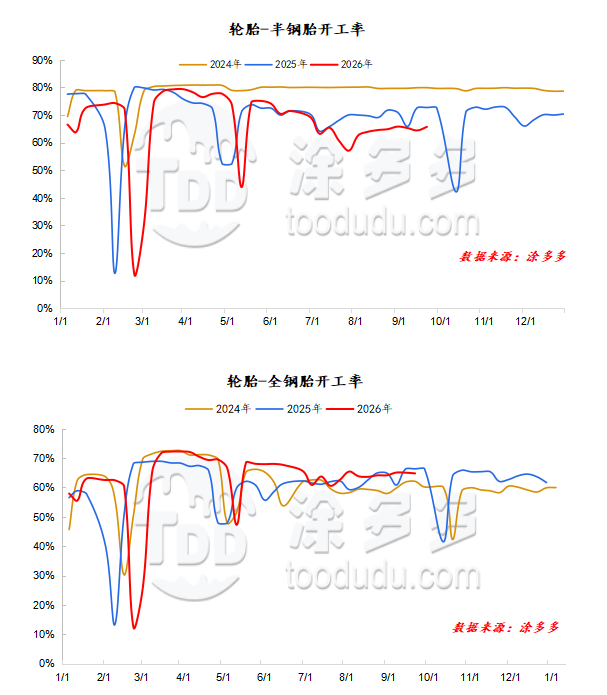
The operating rate for Chinese semi-steel tires was 66%. The operating rate for Chinese all-steel tires was 65%.
During the period, the resumption of production at semi-steel tire maintenance enterprises drove a recovery in operating rates, but most enterprises remain in a production-control state, limiting the overall operating rate improvement. For all-steel tires, some maintenance enterprises resumed production, but with recent continuous increases in raw material prices, certain specifications are operating at a loss, and enterprises' willingness to control production has strengthened, dragging operating rates lower.
6. Industry News This Week
Wuxi Hengheng White Carbon Black Rice Husk Ash Water Glass Technical Upgrade: Annual Carbon Reduction of Nearly 10,000 Tons
Recently, Wuxi Hengheng White Carbon Black Co., Ltd. completed a platform update and public announcement for the energy-saving review of its technical upgrade project to produce 120,000 tons/year of water glass using rice husk ash. The project is located in the New Materials Industrial Park, Donggang Town, Xishan District, Wuxi City, focusing on the green transformation of upstream raw materials for precipitated white carbon black.
The project utilizes 11,383.90 square meters of existing buildings, eliminates two original quartz sand water glass production lines, and procures 59 sets of production and auxiliary equipment including rice husk ash belt conveyors, rice husk ash feeders, bag breakers, rice husk ash dosing scales, liquid sodium silicate reactors, sodium silicate mixing tanks, chamber filter presses, induced draft fans, and air compressors. It also reuses existing water purification equipment (4 centrifugal pumps), 2 forklifts, and 1 transformer as public auxiliary equipment.
The project adopts a liquid-phase production process, primarily including: batching, slurry preparation, liquid sodium silicate reaction, refining, and filter cake washing. The project uses rice husk ash reacted with sodium hydroxide to replace the original quartz sand process for producing liquid water glass. After the upgrade, production capacity remains unchanged at 120,000 tons/year of liquid water glass.
Relevant approval work is proceeding steadily. Environmental impact assessment was initiated in 2025 and has received approval. The Wuxi Municipal Data Bureau issued an energy-saving review opinion on June 29, 2026, and the credit platform completed the energy-saving review information update on September 7. The project is currently in the pre-construction preparation phase, with the next steps being the demolition of old production lines, equipment procurement, and installation.
The traditional quartz sand water glass process has high energy consumption and large carbon emissions. This project replaces quartz sand with agricultural solid waste rice husk ash. Upon completion, it will reduce carbon dioxide emissions by 9,657.78 tons annually, significantly cutting fossil energy consumption.
Wuhai Anlun 280,000-Ton Carbon Black Project Reaches Substantial Progress
Recently, the Guofu Furnace for the carbon-based new materials comprehensive application project of Wuhai Anlun New Technology Co., Ltd. was successfully hoisted into place, marking the project's transition from the civil construction phase to the core equipment assembly phase, laying a key foundation for subsequent engineering construction, equipment installation integration, and on-schedule commissioning.
The project is located in the Low-Carbon Industrial Park, Hainan District, Wuhai High-Tech Industrial Development Zone, Inner Mongolia. Construction officially commenced on April 9 this year. It is a key carbon-based new materials benchmark project in Wuhai. Wuhai Anlun New Technology Co., Ltd. is a joint venture established by Shanxi Anlun Chemical Co., Ltd. and Inner Mongolia Guangju New Materials Co., Ltd., positioned as a technology enterprise focused on carbon-based new materials R&D and industrialization.
The project covers approximately 703 mu, with a total investment of 3.17 billion yuan. Upon completion and commissioning, it is expected to achieve an annual total output value of approximately 6 billion yuan and annual taxes of approximately 300 million yuan, providing approximately 500 jobs. This is of significant importance for driving local industrial upgrading and stable employment. The project plans to construct four core production units and supporting public auxiliary and environmental protection facilities: an annual 280,000-ton carbon black production unit, an annual 2.63-million-ton upgraded coal pyrolysis unit, an annual 450,000-ton coal tar processing unit (including 300,000 tons/year of high-temperature coal tar and 150,000 tons/year of low-temperature coal tar processing sub-units), and an annual 150,000-ton LNG supporting unit.
The core of this project employs the Guofu Furnace low-rank coal quality-based utilization patented technology, which is also where the value of the hoisted core equipment lies. Through this process, low-rank coal enters the Guofu Furnace for pyrolysis, producing upgraded coal and pyrolysis gas. The pyrolysis gas serves as a stable production gas source for the carbon black unit on one hand, and on the other, enables full resource utilization of carbon black tail gas, reducing pollutant emissions. Additionally, surplus pyrolysis gas is purified to produce LNG. The upgraded coal is transported to downstream enterprises in the park via a hot-char direct supply mode, eliminating the need for secondary drying and significantly reducing downstream production energy consumption.
In terms of industrial chain layout, the project leverages the park's integrated advantages by directly piping coal tar from Inner Mongolia Guangju New Materials as carbon black raw material, eliminating tanker truck transportation, reducing logistics costs, and building a closed-loop material circulation system within the park to achieve upstream-downstream industry coupling. The Guofu Furnace heavy-lift hoisting was undertaken by China Chemical Eleventh Construction Company. The successful completion of the heavy-lift hoisting is a key milestone in project construction.
According to the project construction plan, the main structures are expected to be topped out in November this year, with major equipment installation completed by January 2027, and project completion and commissioning by the end of April 2027. Wuhai Hainan District is an important coal chemical agglomeration area in western Inner Mongolia, with a long-term focus on clean and efficient coal conversion. The project will fill the gap in the local carbon black industrial chain, drive the transformation of traditional coal chemicals toward high-value-added carbon-based new materials, and achieve quality-based gradient utilization of coal resources. After commissioning, the project will further improve the Wuhai region's integrated circular industrial chain of coal-pyrolysis-coal tar-carbon black-LNG, enhance the regional coal comprehensive utilization level, and support the green, low-carbon, and high-quality development of the local coal chemical industry.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.









